 how-to
Workers' Comp Settlement Process in Mississippi
Table of Contents
- Understanding the Workers' Comp Settlement Process
- Filing Your Workplace Injury Claim
- Medical Treatment and Authorized Providers
- Wage-Loss Benefits and Disability Ratings
- Workers' Comp Settlement After Surgery
- Mississippi Workers' Comp Settlement Mediation
- Settlement Approval and Release Requirements
- Settlement Calculations and Lump-Sum Payments
- Frequently Asked Questions
Last Updated: October 11, 2026
Understanding the Workers' Comp Settlement Process
A workers' compensation settlement is an agreement between you and the insurance carrier to resolve your claim for a specific amount. The workers comp settlement process in Mississippi involves filing your claim, receiving medical treatment, and negotiating a final settlement. (Source: the U.S. Department of Labor's website)
Once you settle, you receive a lump-sum payment in exchange for releasing the insurance carrier from future liability. Understanding the workers comp settlement process before you sign is critical.
Many workers feel uncertain about whether to settle or keep their claim open. The information below clarifies your options.
Filing Your Workplace Injury Claim
Your claim begins when you report your injury to your employer. The faster you report, the stronger your claim.
Reporting the injury to your employer
Tell your supervisor or manager about your injury immediately. Put the report in writing with the date, time, location, and what happened. Keep a copy for your records.
Your employer must give you a claim form within a few days to notify the insurance carrier. Do not delay reporting; waiting weeks or months raises questions about whether the injury occurred at work.
Submitting your claim to the insurance carrier
The insurance carrier must respond to your claim within a specific timeframe. If accepted, you become eligible for medical benefits and wage-loss benefits.
If denied, you can request a hearing before an administrative judge. Documentation of your injury and medical records strengthens your position. If you need assistance navigating a denial or complex claim issues, Workers Compensation representation can help ensure your rights are protected.
Medical Treatment and Authorized Providers
Once accepted, the insurance carrier must pay for reasonable and necessary medical treatment. The carrier usually has a list of authorized providers or may require you to see their medical provider first.
If you need treatment beyond the initial provider's recommendation, request authorization. Keep all medical records and bills to support your claim value.
Wage-Loss Benefits and Disability Ratings
Wage-loss benefits replace a portion of lost wages while you cannot work, based on your average weekly wage and disability status.
Temporary disability versus permanent disability
Temporary disability benefits apply while you recover and cannot work. Once you reach maximum medical improvement (your condition will not improve further with treatment), your disability status changes.
Permanent disability means your injury causes lasting limitations. You may receive permanent disability benefits even if you return to work at lower pay. The insurance carrier may require an independent medical examination to determine your disability rating.
A disability rating is a percentage assigned by medical professionals reflecting how your injury limits your ability to work. Higher ratings mean higher benefit amounts.
Workers' Comp Settlement After Surgery
If your injury requires surgery, you typically cannot settle until after surgery and recovery, when your doctors know your final medical status. Settling too early may not provide enough money for ongoing treatment.
After surgery, you need time to reach maximum medical improvement, usually several months. Your surgeon's reports on recovery and permanent limitations become part of your settlement calculation.
Mississippi Workers' Comp Settlement Mediation
Mediation is a common step before a formal hearing. A neutral third party facilitates negotiation between you and the insurance carrier without deciding your case.
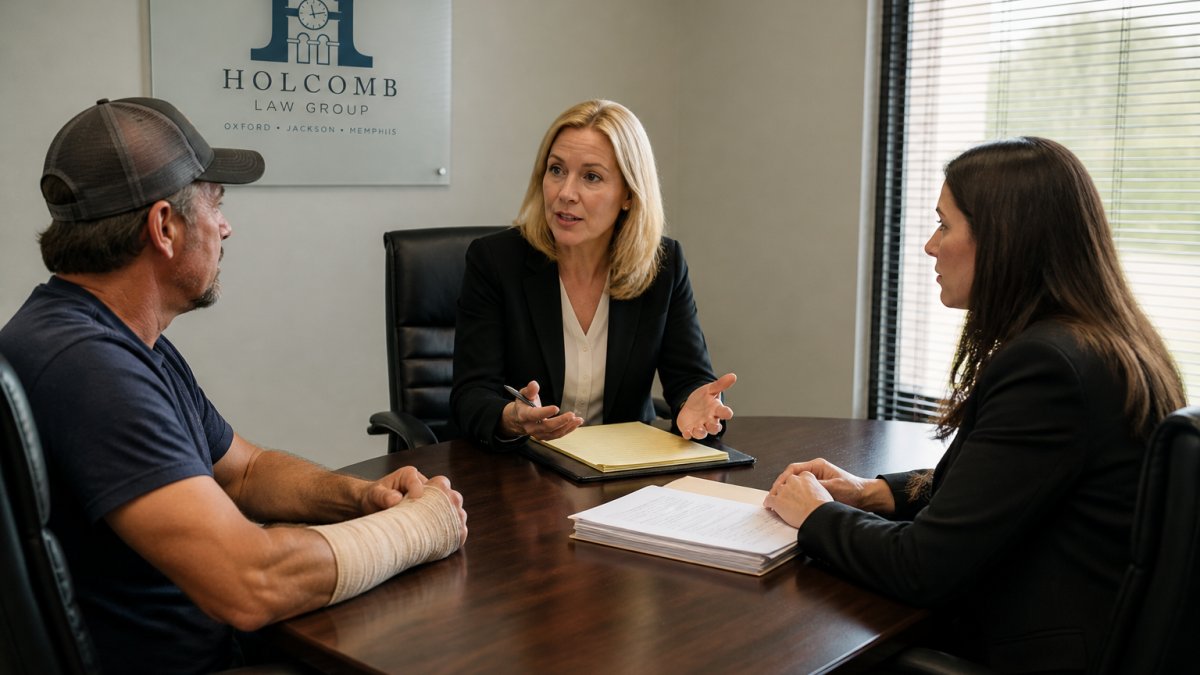
Mediation often results in settlement because both parties avoid the cost and uncertainty of a hearing.
If mediation fails, your case moves to a hearing before an administrative judge who decides disputed issues.
Settlement Approval and Release Requirements
Before your settlement becomes final, it must be approved by the Mississippi Workers' Compensation Commission. Without approval, your settlement is not binding and payment does not occur.
The Commission's review process
When you and the insurance carrier reach a settlement agreement, the carrier submits documents to the Commission. The Commission reviews the agreement to ensure it is fair, reasonable, and complies with state law.
The Commission examines whether your average weekly wage was calculated correctly, your disability rating is supported by medical evidence, the settlement aligns with statutory formulas, you understood the terms, and the agreement complies with state law.
The review typically takes 2-4 weeks. The Commission may request additional information or reject the settlement if it finds issues.
Understanding settlement releases and finality
A settlement release is a legal document you sign accepting the settlement amount in exchange for releasing the insurance carrier from all future liability.
The release should clearly specify all past medical expenses and wage-loss benefits covered, whether future medical expenses are included, your permanent disability award, and the effective date.
Read the release carefully. If language is unclear, ask for written clarification. Do not sign with blank spaces or undefined terms. (Source: the Social Security Administration's guidelines on disability)
Open medical care versus full and final settlement
The type of settlement you choose determines your rights after approval.
Open medical care settlement: The insurance carrier continues paying for treatment related to your injury indefinitely.
Full and final settlement: You receive one payment covering past wage-loss benefits, permanent disability, and all future medical expenses. After approval, you pay for additional treatment yourself and cannot return for more money.
The choice depends on your injury's stability and medical prognosis. Workers with serious injuries or chronic pain should consider open medical care. Workers with stable injuries may accept a full and final settlement.
What happens after Commission approval
Once approved, the insurance carrier issues payment within 30 days. If you have an attorney, payment goes to their trust account; they deduct their fee and costs, then send you the remainder. Without an attorney, payment goes directly to you.
After payment, your claim is closed. You are no longer eligible for temporary disability or wage-loss benefits. Any medical treatment after settlement is your responsibility, unless you chose open medical care.
Settlement Calculations and Lump-Sum Payments
Your settlement amount is calculated using a statutory formula based on your average weekly wage, disability rating, and whether you receive open or closed medical care.
How average weekly wage is determined
Average weekly wage (AWW) is the foundation of your settlement calculation. It is typically your gross weekly earnings in the 52 weeks before your injury, or based on the time you did work if hired mid-year.
Your AWW includes regular wages, overtime, bonuses or commissions that are part of normal pay, and tips. It does not include unused vacation pay, severance pay, or one-time bonuses.
Disputes over AWW are common. If you worked multiple jobs, had irregular hours, or received variable pay, challenge the carrier's calculation with pay stubs, tax returns, or employer statements.
Disability rating and benefit calculation
Your disability rating is a percentage assigned by medical professionals based on your injury and its effect on your ability to work.
Disability ratings range from 0% to 100% and directly determine your settlement amount.
The formula for permanent partial disability benefits is: Average Weekly Wage × Disability Rating Percentage × Statutory Multiplier. The statutory multiplier varies by injury type and body part under Mississippi law.
Factors that increase or decrease settlement value
Factors that increase settlement value:
- Higher disability rating (more permanent impairment)
- Higher average weekly wage
- Younger age (more working years remaining)
- Ongoing medical needs (if you choose open medical care, the carrier's future obligation increases value)
- Documented complications or worsening condition
- Strong medical evidence supporting your limitations
Factors that decrease settlement value:
- Lower disability rating
- Lower average weekly wage
- Older age (fewer working years remaining)
- Stable condition unlikely to require future treatment
- Pre-existing conditions that complicate causation
- Gaps in medical treatment or documentation
Statutory benefit limits
Mississippi law sets maximum and minimum benefit amounts. Your settlement cannot exceed the statutory maximum for your injury type, even if your calculation suggests a higher amount. Conversely, your settlement must meet the statutory minimum.
These limits change annually. As of 2026, the maximum weekly benefit for temporary disability is set by statute; permanent disability benefits follow separate formulas. Your attorney or the insurance carrier can tell you the current limits that apply to your case.
Open versus closed medical care and settlement value
If you choose an open medical care settlement, the insurance carrier's ongoing obligation for future medical expenses is factored into the settlement amount. This typically results in a lower lump-sum payment because the carrier retains liability for future treatment.
If you choose a full and final settlement, the lump sum must account for all anticipated future medical expenses. The carrier estimates your likely future treatment costs and includes that estimate in the settlement. If your condition is stable, this amount may be modest.
Evaluating a settlement offer
When the insurance carrier proposes a settlement amount, ask for a written breakdown showing:
- Your calculated average weekly wage
- Your disability rating
- The statutory multiplier used
- The base permanent partial disability benefit
- Any adjustments for age, future medical care, or other factors
- The total settlement amount
Compare this breakdown to your understanding of your injury and prognosis. If the disability rating seems too low, request the medical evidence supporting it. If your AWW appears incorrect, provide documentation of your actual wages.
Disputes over settlement calculations are common and often resolved through negotiation or mediation. Do not accept an offer you believe is unfair without exploring your options.
Payment timing and process
Once the Mississippi Workers' Compensation Commission approves your settlement, the insurance carrier issues payment. Payment typically occurs within 30 days of approval, though timing can vary based on administrative processing.
If you have an attorney, the payment goes to your attorney's trust account. Your attorney deducts their fee and costs, then sends you the remainder.
If you do not have an attorney, payment goes directly to you. You receive the full settlement amount.
The payment is usually issued as a check or electronic transfer. Confirm the payment method with the insurance carrier before approval.
Frequently Asked Questions
What is the waiting period for workers' comp benefits in Mississippi?
In Mississippi, there is typically a three-day waiting period before temporary disability benefits begin. However, if the disability extends beyond two weeks, benefits are paid retroactively from the date of injury. The exact waiting period and benefit structure depend on your specific injury and claim circumstances. Consult with a workers' compensation attorney to understand how this applies to your case.
Will surgery increase my workers' comp settlement?
Surgery can impact your workers' comp settlement value, particularly if it results in permanent disability or ongoing medical needs. The settlement amount reflects reasonable and necessary medical treatment, lost wages, and permanent disability ratings. After surgery, your maximum medical improvement status and any work restrictions will be reassessed. An attorney can help you understand how surgical outcomes affect your settlement negotiations.
What happens during workers' comp settlement mediation?
During mediation, you, your employer's insurance carrier, and a neutral mediator meet to discuss settlement options. The mediator helps both parties identify common ground and explore settlement values. You present evidence of your injury, medical treatment, lost wages, and permanent disability. The goal is to reach a mutually acceptable settlement agreement without proceeding to a hearing before an administrative judge.
What should I review before accepting a workers' comp settlement?
Before accepting any settlement, review the total amount, what it covers (medical benefits, wage-loss, permanent disability), and whether future medical expenses are included or excluded. Understand whether you're accepting a full and final settlement (closing future medical care) or retaining open medical benefits. Have an attorney review the settlement release to ensure you're not waiving rights you need to protect. Verify all calculations are accurate based on your average weekly wage and disability rating.